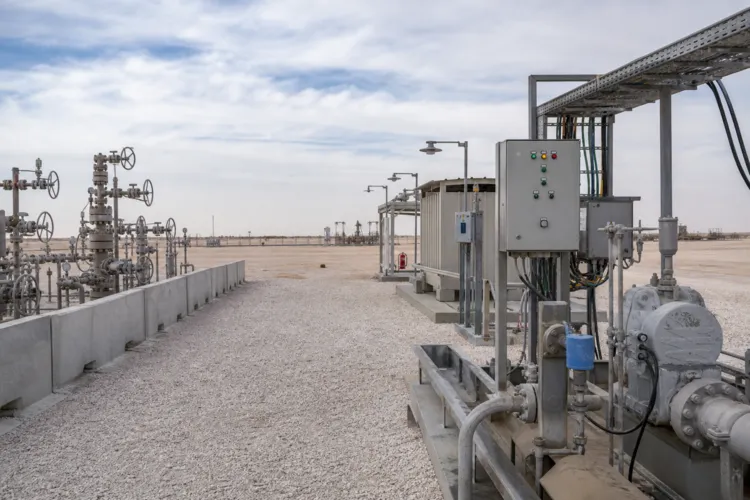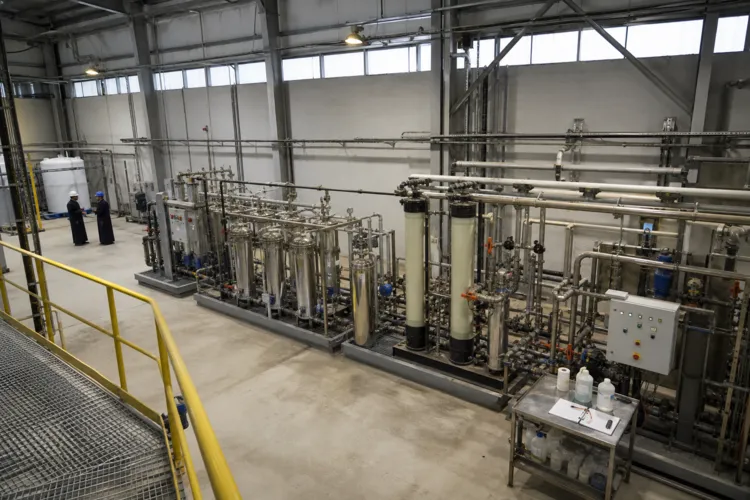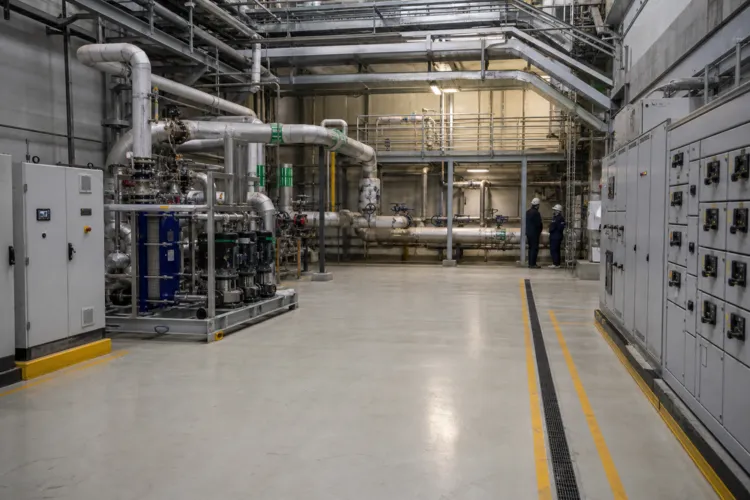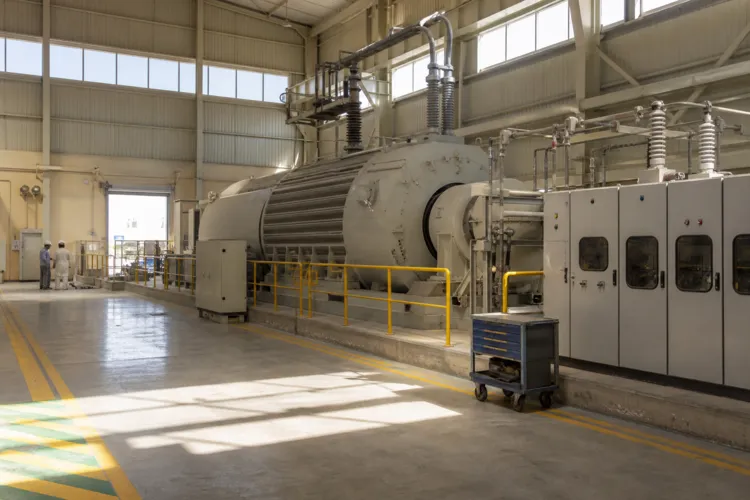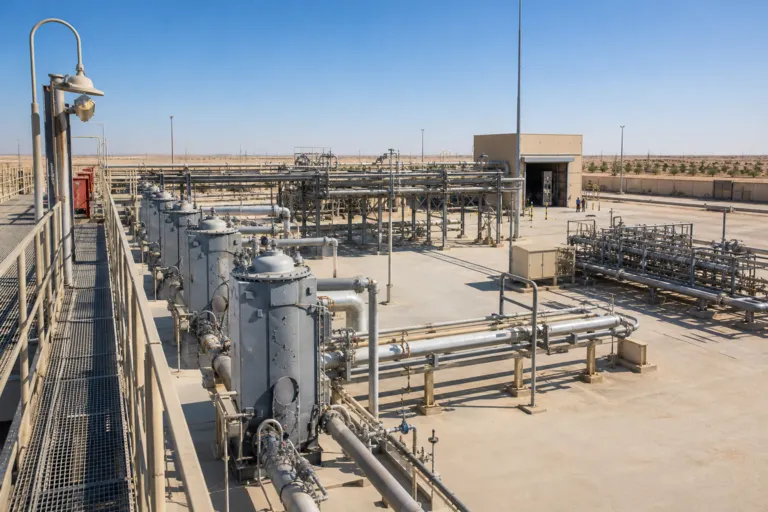
Saudi Arabia’s push to scale carbon capture and storage is increasingly framed around hub infrastructure rather than isolated projects. Within that context, the Jubail carbon capture hub is described as a flagship effort designed to centralize CO₂ capture, conditioning, transport, and permanent storage so multiple emitters can connect. Several sources link this build-out to a national objective of capturing and storing 44 million tons of CO₂ per year by 2035. The Jubail project is repeatedly presented as an anchor for industrial decarbonization in a dense industrial zone, with the ability to expand beyond one emitter as additional sources of CO₂ connect.
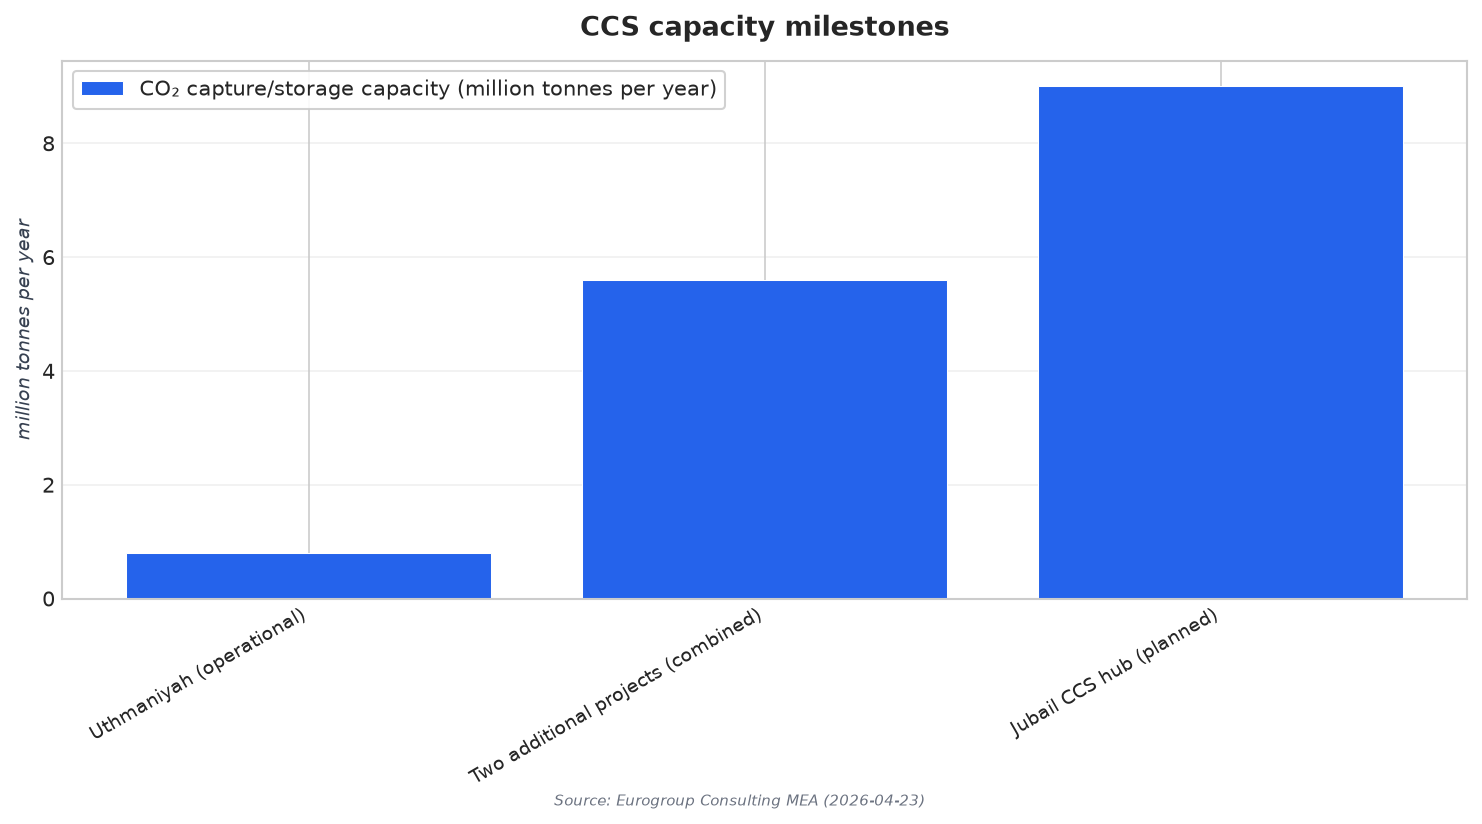
Across sources, the project is commonly described as expected to store up to 9 million tons of CO₂ annually, with completion or targeted operation stated as 2027–2028. One description adds that this annual amount is described as equivalent to removing nearly 2 million passenger cars from the road every year, offering a simple way to understand the scale being targeted. Another market-focused description says the hub is designed to capture 9 million tonnes annually starting in 2027 from Aramco gas plants at Wasit, Fadhili, and Khursaniyah, alongside emissions from neighboring petrochemical and steel facilities. This framing is what turns the initiative into shared network infrastructure, not just a single capture unit.
From Planning to Construction: The 2025 Contracting Signal
Sources describing Saudi Aramco’s CCUS program emphasize that Jubail shifted from planning into execution in 2025. Between 2021 and 2024, the hub is described as being primarily in planning and partnership formation, including a joint development agreement involving SLB and Linde. The pivotal change cited is a February 24, 2025 award of a USD 1.5 billion engineering, procurement, and construction contract to Larsen & Toubro, described as covering gas compression and dehydration facilities tied to the hub. Another source summarizes the same turning point by stating Aramco deployed over USD 1.7 billion in contracts in 2025 for the flagship Jubail project, reinforcing the message that delivery is being funded and contracted, not only announced.
Jubail also sits within a wider national narrative about building experience and expanding capacity. Sources note Saudi Arabia already operates the Uthmaniyah CCS project, targeting 800,000 tons of CO₂ per year, and describe today’s operational CCUS capacity as 0.8 million tons per year. In the same set of materials, two additional projects are described as each targeting 2.8 million tons per year and expected online by 2027–2028. These references are often used to position Jubail as the step-change project in a growing set of domestic storage and capture sites, with hub design enabling more emitters to connect over time.
Some sources extend the story beyond domestic capture by highlighting a service-provider ambition. One analysis describes a strategy that includes cross-border carbon flows, where CO₂ from Asia could be transported by sea and permanently stored in Saudi geological reservoirs. In that framing, the shared model of the Jubail carbon capture hub supports the idea of aggregating CO₂ from multiple sources into one system. Market-oriented projections in the sources also underscore that CCS is being discussed as an economic sector as well as infrastructure. One forecast values Saudi Arabia’s CCS market at USD 107.93 million in 2025, growing at a 15.2% CAGR to USD 334.79 million by 2033, while another forecast describes a broader CCUS market rising from USD 68.9 million in 2025 to USD 146.0 million by 2032 at an 11.6% CAGR.
What is the Jubail carbon capture hub designed to do?
What storage capacity is cited for the Jubail CCS hub, and when is it expected to operate?
What contracts signaled the move into construction during 2025?
What existing CCS capacity is referenced in Saudi Arabia today?
How do the sources describe Saudi Arabia’s wider CCS market outlook?
Talk to us for your needs in:
-
Energy Efficiency Strategy & Feasibility
-
Renewable Energy Strategy & Investment Advisory
-
Digital Energy & Smart Grid Strategy
-
Market Entry Strategy
-
Sustainability & Impact Strategy
-
Energy Project Governance & PMO Advisory
-
Energy Market Research
-
Energy Stakeholder & Customer Research
-
Energy Market Intelligence
-
Energy Feasibility & Investment Assessment
-
Energy Sector Benchmarking & Performance Strategy